Governor Hochul has said that affordability comes first, however this post shows that her Regional Greenhouse Gas Initiative (RGGI) record says otherwise. In early September I posted an article about the impact on consumer costs that I fully documented. This post revises my cost estimates using the Potomac Economics report “Quarterly Report on the New York ISO Electricity Markets Second Quarter of 2026” that includes data that I previously had to assume. It also adds complete 2025 data and the results of the September 2026 RGGI auction.
I have been involved in the RGGI program process since its inception and have been writing about problems with the RGGI program here. I have worked on every cap-and-trade program affecting electric generating facilities in New York including RGGI, the Acid Rain Program, and several Nitrogen Oxide programs, since the inception of those programs. The opinions expressed in this post do not reflect the position of any of my previous employers or any other organization I have been associated with. These comments are mine alone. I acknowledge the use of Perplexity AI to generate material included in this document.
Background information about RGGI is available here. I have also revised the technical support document provided earlier that explains the calculation methodology and provides cost background information.
The affordability claim meets reality
Governor Hochul has repeatedly told New Yorkers that affordability is her top priority. Her 2026 agenda and the May 2026 relief package were both framed explicitly as responses to high utility and gasoline costs. That framing invites a simple test: have the energy policies her Administration has advanced and defended made electricity more or less expensive?
On the RGGI allowance price alone, the answer is not close. When Hochul took office in late August 2021, the most recent completed auction — Auction 52 on June 2, 2021 — had cleared at $7.60 per ton. The first auction after she became Governor, Auction 53 in September 2021, cleared at $9.30. Auction 72 on June 3, 2026, cleared at $35.00 per allowance. The most recent completed auction as of this writing, Auction 73 on September 9, 2026, cleared at $37.65 per allowance for total regional proceeds of about $1,074.4 million. New York proceeds were $262.4 million on the sale of 6,970,201 allowances. At the time this was written, the secondary market for RGGI allowances is trading above $37.00 per allowance.
Measured from the first full auction of her tenure, that is an increase of $28.35 per ton, or 305% over a five-year period. The RGGI carbon price has multiplied more than four times over on her watch, and it did so with the active participation of the state agencies she oversees — Department of Environmental Conservation (DEC), New York State Energy Research & Development Authority (NYSERDA), and the Department of Public Service (DPS), all of which take part in RGGI program design, auction administration, and the decisions that determine how aggressively the RGGI allowance cap is tightened. There is no doubt that the recent price rise is related at least in part to the recently approved DEC amendments that mandate an arbitrary auction cap reduction consistent with state laws but are inconsistent with emission reductions that can be expected from RGGI auction revenue investments.
RGGI consumer costs
In August DEC and NYSERDA amended the implementing regulations for an update to the RGGI rules. The press release describing the final amendments claims RGGI investments have generated “nearly $12 billion in net ratepayer savings” against roughly $2 billion invested. This benefit cost ratio only considers ratepayer costs of RGGI allowance auction investments. The Technical Support Document describes the source of those values, and it clearly only refers to auction revenues.
I have made this point in prior posts and it bears repeating because the Administration’s messaging has not acknowledged what RGGI costs ratepayers. In the Regulatory Impact Statement for the recent amendments, the analysis of RGGI costs uses a non-binding-cap reference, using allowance prices the market has already passed. RGGI requires fossil-fueled generators to hold an allowance for every ton of CO2 they emit. That allowance price becomes a variable operating cost for the generator and part of their bid to market. In New York’s marginal-price wholesale electricity market, when an emitting generator sets the clearing price for an interval, its allowance cost is part of the bid and can raise the total energy price paid to every accepted resource in that interval — not merely reimburse the emitting unit for the allowances it bought. Non-emitting and even imported resources can collect the higher price despite bearing little or none of the underlying RGGI cost themselves.
What the Potomac report changed
My earlier estimate had to assume which types of units set the wholesale price. Because NYISO does not publish the price-setting unit for each interval, I originally assumed that modern combined cycle units set the price 60% of the time, gas-fired boilers 35% of the time, and oil-fired combustion turbines 5% of the time, and that a RGGI-affected unit set the price in every hour. The Potomac Economics quarterly report describes how often each fuel type is the marginal unit in the real-time market. In the first quarter of 2026 natural gas combined cycle units were marginal in 67% of intervals and oil units in 19%. In the second quarter combined cycle units were marginal in 84% of intervals, other gas units in 28%, hydro in 25%, wind and solar in 24%, and oil in none. The percentages add up to more than 100% because more than one unit can be marginal when transmission constraints bind.
Two conclusions follow. First, oil units matter in some seasons and not others, so a fixed annual share is not appropriate. Second, RGGI-affected units do not set the price in every hour, so applying a RGGI cost to all the energy used in New York overstates the cost. I revised the spreadsheet to address both points. For each year I used EPA Clean Air Markets data for New York’s RGGI units to calculate the average operating hours of five unit types: modern combined cycle units, gas-fired and oil-fired boilers, and gas-fired and oil-fired combustion turbines. I assumed that the most expensive type of unit operating sets the price during its operating hours, the next most expensive type sets the price for its additional hours, and so on down to the combined cycle units. The rest of the year, between 25% and 33% of the hours depending on the year, is assigned to hydro, imports, renewables, and nuclear with no RGGI cost at all. Each unit type’s RGGI cost is its CO2 rate times the allowance price, applied to its share of the Gold Book total energy.
Potomac uses the same calculation for the equivalent energy cost of RGGI: the allowance price times the emission rate times the heat rate. It reports that the roughly $20 per ton increase in RGGI prices from the second quarter of 2025 increased marginal production costs by about $9 per MWh. Using Potomac’s natural gas emission factor of 0.059 tons per mmBtu and an efficient 7,500 Btu/kWh gas unit, $20 × 0.059 × 7.5 = $8.85 per MWh, so my approach is consistent with the market monitor’s. I think the new central estimate is conservative. My approach has combined cycle units setting the price in only 37% to 47% of the hours, while Potomac found them marginal in 67% to 84% of intervals in the first half of 2026. I also included a fleet-average estimate that assumes the average RGGI unit sets the price in all hours as an upper bound.
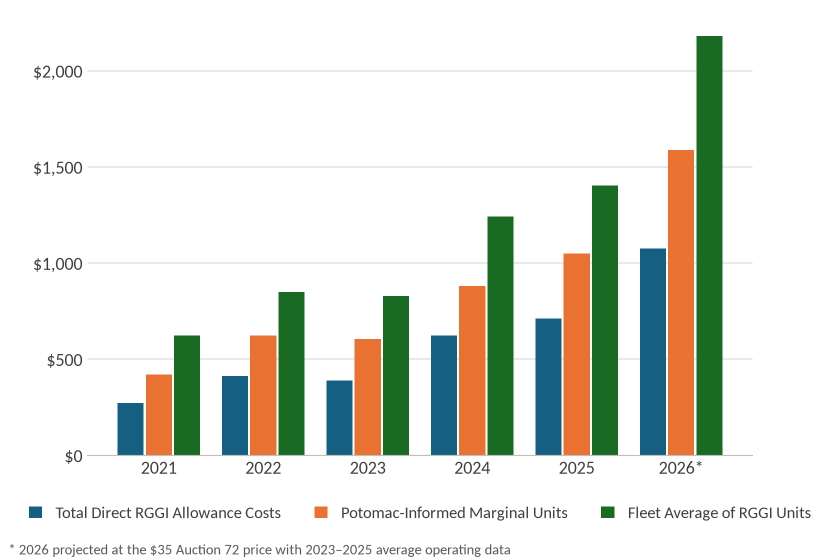
Table 1 lists the total annual estimated RGGI costs. The NYSERDA and DEC analyses only go through 2024, but complete emissions and auction data are now available for 2025, so my estimates run through 2025. I also projected a 2026 cost using the Auction 72 $35 allowance price and average 2023–2025 operating data. The Administration messaging only considers the cost of allowances sold in auction – the total direct RGGI allowance cost row. As described in the Technical Support Document I also calculated estimates that include the variable operating costs in the wholesale electric market. The Potomac-informed marginal units row is my central estimate. The fleet average row is an upper bound that assumes an average RGGI unit sets the price in every hour. When the wholesale market costs are included, the central estimate is about 50% higher than the direct allowance cost and the upper bound is about double, and costs are rising steeply (Figure 1). Between 2021 when Hochul took office and 2025 the central estimate of annual RGGI costs increased $630 million, or 2.5 times. Holding everything else constant at the Auction 72 $35 allowance price, the 2026 central estimate is $1,587 million, 3.8 times the 2021 cost. At the Auction 73 price of $37.65 it would be $1,707 million.
Table 1: Total Annual RGGI Costs($ millions)
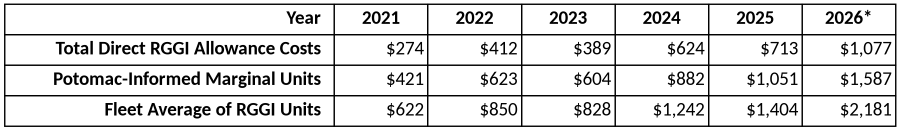
Notes: 2026 uses 2023-2025 average energy and generation-weighted unit rates. 2026 YTD average = Auctions 71-73. Results scale linearly with price.
Figure 1: Total Annual RGGI Cost Trend ($ millions)
I also estimated the annual cost to residential customers. A typical New York residential electric customer uses approximately 570 kWh per month (about 6.8 MWh annually). Table 2 lists the annual estimated RGGI costs for residential consumers. The direct allowance cost row spreads the total direct allowance cost over all the electricity used in the state. If the only costs considered are the direct cost of allowances, the estimated costs are substantially lower than when the wholesale electric market costs are included. For example, in 2025 allowance costs were $37 a year, but the central estimate of the total cost was $54 and the upper bound was $73. Between 2021 when Hochul took office and 2025 the central estimate of residential annual RGGI costs increased from $23 to $54, or 2.4 times. Holding everything else constant at the Auction 72 $35 allowance price, the 2026 central estimate is $85 a year, 3.7 times the 2021 cost, and the upper bound is $117. That represents 5.1% to 7.0% of a typical residential electric bill. At the Auction 73 price of $37.65 the range is $91 to $125 a year. This continues a trend (Figure 2) that I expect to continue to grow.
Table 2: Annual Residential Cost of RGGI ($)
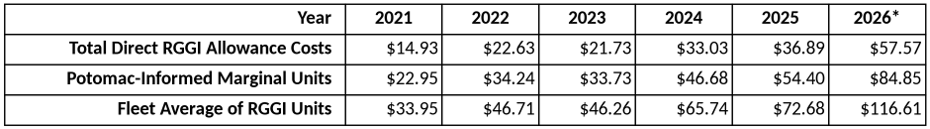
Figure 2: Annual Residential Cost of RGGI ($) Trend
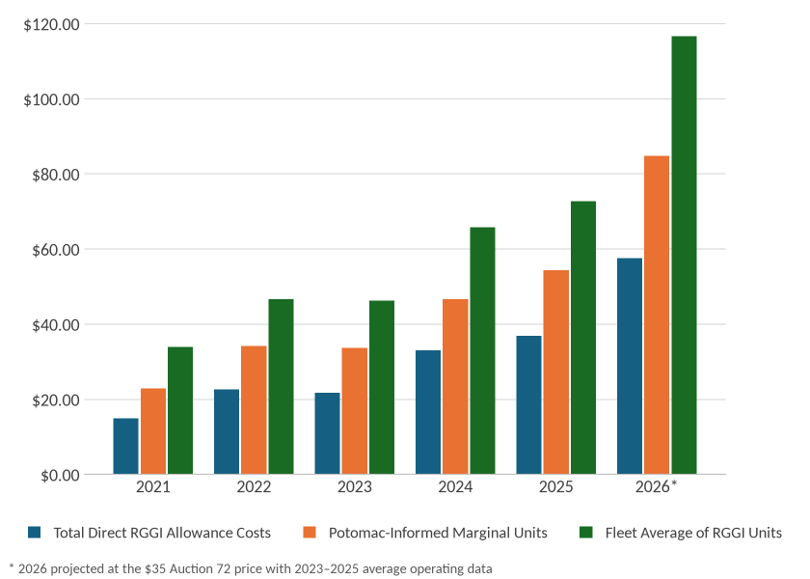
These cost estimates show the RGGI price increase does not stay contained to a line item on the emitting generator’s books. It works its way into wholesale prices, and from there into what load-serving entities — and retail customers — pay for the electric commodity they consume.
None of that disappears because the state collects auction revenue and calls the proceeds an “investment.” Consumers pay the higher embedded cost first, through what they are charged for each kilowatt of electricity. Only a portion of the allowance proceeds comes back later, to selected programs, or selected bill-credit recipients. A household that does not qualify for a program, cannot front the money for an efficiency upgrade, or simply does not live in a service territory where a credit is applied still pays the RGGI-driven cost with nothing returned.
The contradiction Hochul has not had to answer
The same Administration that says it wants to protect New Yorkers from high energy costs signed off on a Third Program Review that lowers the regional RGGI cap sharply through 2037, with steeper annual reductions from 2027 through 2033. A tighter cap means a smaller supply of allowances at a time when there is growing electricity demand — precisely the dynamic that has already pushed the allowance price up 40 percent in a single quarter this year. RGGI’s own market monitor has acknowledged the resulting affordability and scarcity concerns are real, not hypothetical.
An affordability agenda should not rest on imposing a rising energy charge today while pointing to a modeled, largely unverified, multi-year savings projection as the offset. Governor Hochul cannot credibly claim affordability is her governing priority while her Administration has overseen — and just locked in further tightening of — a program whose price has more than quadrupled on her watch.
Discussion
In my opinion, the cost of RGGI allowances is another buried cost of the clean energy transition that very few people know about. In 2025 the impact of RGGI allowances accounted for $54 to $73 per year, or 3.2% to 4.3% of a typical residential electric bill based on the most recent EIA data ($139.53 per month in 2024). Projecting the latest sharp rise in allowance prices raises the costs to $85 to $117 per year, or 5.1% to 7.0% of a typical residential electric bill. At a time when there is an energy affordability crisis it is fair to ask whether New Yorkers are willing to pay for this program?
If the Administration wants to prove a positive benefit/cost ratio then they should request that NYISO provide the wholesale market impact calculated with the hourly data that only they have. For the benefits they should only consider savings actually returned to consumers, broken out from savings that are committed but not yet delivering measured savings. They should also only include verified, evaluated-and-measured bill savings — not modeled lifetime projections — compared against the total full cost.
Conclusion
The combination of New York’s wholesale electric-market structure and the recent sharp increase in RGGI allowance prices means that the program is no longer a marginal cost with little consequence for consumers. It is now a meaningful contributor to residential electric bills.
My review of NYSERDA’s reported results indicates that RGGI-funded investments have produced relatively little measured progress toward the program’s core purpose: reducing emissions from the electric generating units subject to the RGGI cap. Using the State’s reported cumulative annualized program benefits, I estimate a cost of approximately $583 per ton of CO2 reduced. Moreover, the RGGI investment-related savings represent only about 4.7% of the electric-sector emissions reductions observed since the program began. Most of the historic reduction appears instead to be associated with fuel switching from coal and oil to lower-emitting natural gas—a transition that offers little opportunity for additional reductions going forward.
That mismatch matters because RGGI is fundamentally a power-sector compliance program, not simply a source of funding for otherwise worthwhile State initiatives. If allowance costs are adding 5% to 7% to residential electric bills, then New York should be able to demonstrate that the revenues are being directed first to cost-effective measures that reduce emissions from RGGI-covered sources, lower customer bills, and help maintain reliable compliance with an increasingly stringent cap.
Governor Hochul has emphasized energy affordability. That commitment should require an independent, transparent review of whether New York’s continued participation in RGGI—as presently designed and implemented—delivers emissions reductions and consumer benefits proportionate to its cost. If it does not, then withdrawal from RGGI, or at minimum a fundamental restructuring of the program and its revenue-allocation rules, should be considered a necessary test of rational energy policy.


